 Steven Millward · · 8 min read
China’s fintech industry shows where the rest of the world is heading
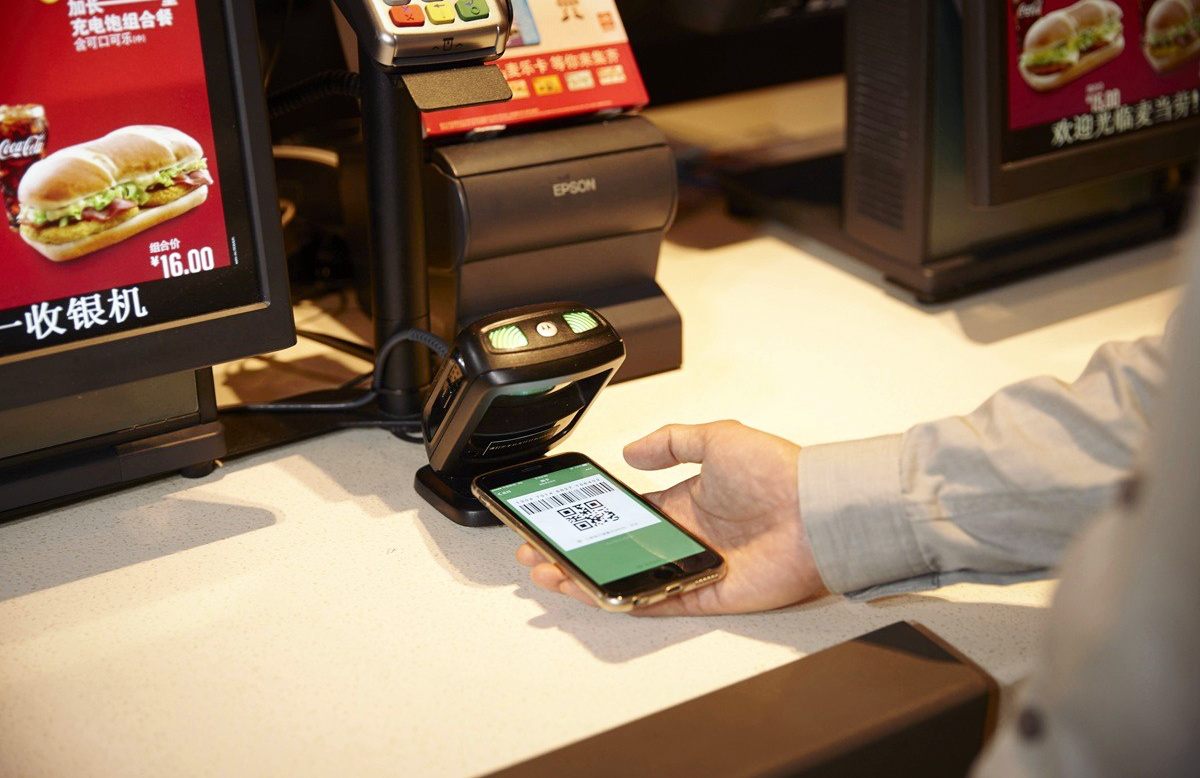
Paying for food with a messaging app. Photo credit: McDonalds.
“We need banking but we don’t need banks anymore,” said Bill Gates two decades ago, predicting the explosion in startups creating web and app-based financial services that we’re seeing right now. With nearly US$11 billion last year invested into so-called fintech startups across Asia, the sector is rivaling online shopping and ride-hailing among the hottest tech arenas.
As this seismic shift takes place, nowhere is it more visible than in China.
At a Starbucks in Shanghai, a punter pays for coffee with a messaging app, waving their phone in front of a barcode scanner. At the sushi joint next door, a customer settles the bill with a mobile wallet app; after lunch, she pays an electricity bill with the same app, and then moves some of her salary into a high interest personal fund. No notes are counted out, no coins bounce and clatter into cash registers, no-one queues at the bank.
“The country leads the world when it comes to total users and market size,” observed a McKinsey report last year about China’s fintech boom, with people entrusting US$1.8 trillion in 2015 to online finance services of all shapes and sizes.
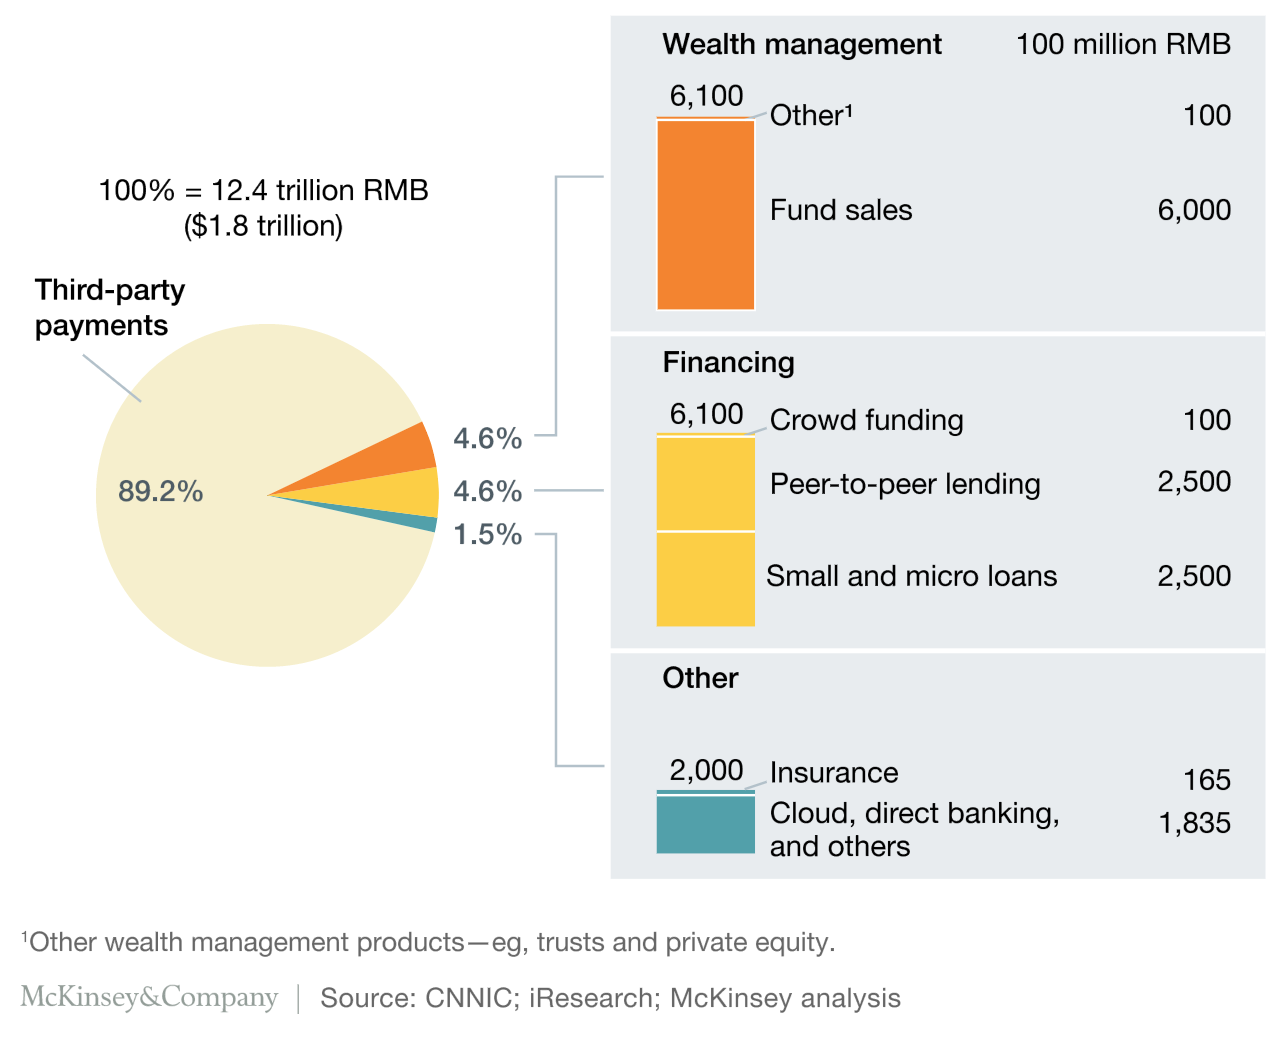
Data is for end of 2015.
China’s overall fintech market is now worth up to US$2.2 trillion.
By looking at China’s main fintech sectors, we can sketch a picture of how this will shape up around the rest of the world.
Scan me: the surge in mobile payments
China’s shoppers pay with their phones more so than people in any other country – a record 195 million did so for in-store and online payments in 2016, rising to an anticipated 332 million in 2020, says Emarketer. Leading the way are WeChat, the turbocharged messaging app from Tencent, and Alipay, the wallet app run by Jack Ma’s Ant Financial.
Apple, Huawei, Samsung, and Xiaomi have their own wallet apps, but they have few functions in comparison to WeChat and Alipay. They’re all fighting over US$1.8 trillion in mobile payments, collectively accounting for 89.2 percent of the transactions in China’s fintech space, according to McKinsey.
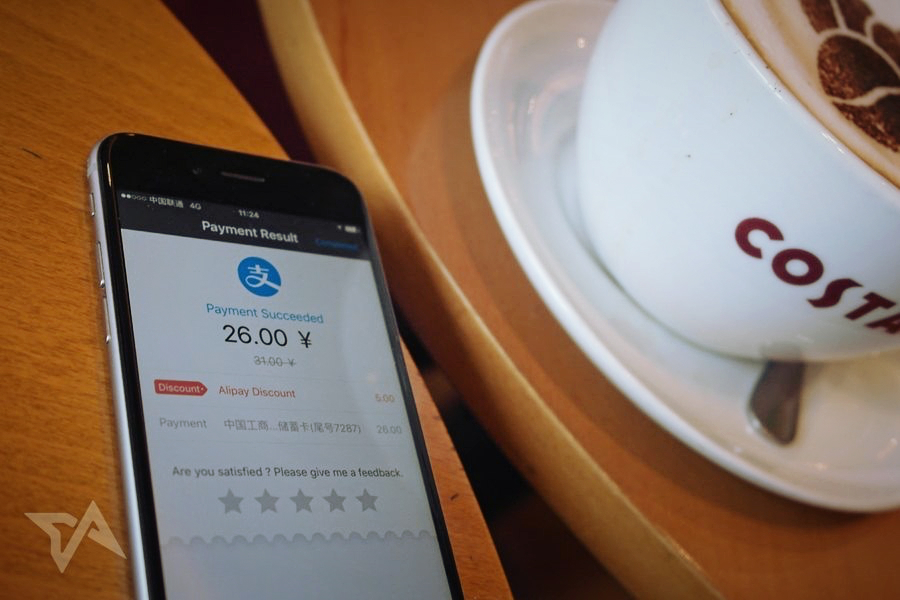
Alipay app shown after being used to pay for coffee.
In China, mobile payments have proved to be a gateway drug for more hardcore fintech services, showing that getting people into wallet apps and giving them a real-world and convenient use case is the first and highest barrier.
Lend me a few bucks: the rise of peer-to-peer loans
Check me out: fixing the credit history conundrum
You can bank on me: the personal finance boom
Watch over me: on-demand online insurance





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.






📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026