 Jonathan Chew · · 5 min read
Meet the company that aims to unify financial services in Indonesia
Even though he was a lawyer by training, the financial services market has always fascinated Gavin Tan. To pursue his passion, Tan left his job at a top public disputes law firm in Singapore and dove headfirst into the fintech space.
His foray into the industry eventually led him to join Aspire, a leading neobank in Southeast Asia for small and medium-sized enterprises, as an early employee. During his time at Aspire, Tan grew more acquainted with the Indonesian fintech market and discovered two major issues.
The first was that there was a lack of good financial application programming interfaces (APIs) in the country, leaving fintech companies in the lurch when they wanted to launch new features or services quickly.
“Without these APIs, it takes a long time for a company to introduce any new financial feature or fintech service,” he says.
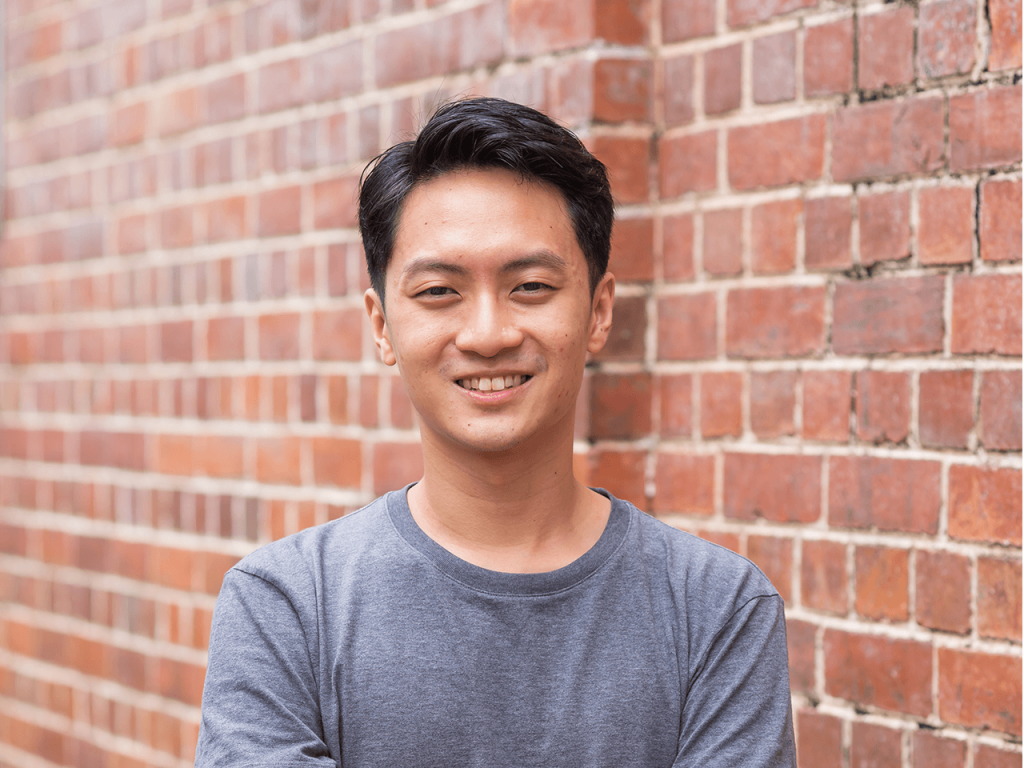
Gavin Tan, CEO and co-founder of Brick / Photo credit: Brick
The second issue was that fintech services and products typically required extremely tedious and manual processes. This led to poor user experiences with high drop-off rates and opened the door to fraud – users would at times send in doctored documentation on these platforms.
“I knew that other fintech companies were facing the same problems, and my friends in fintech were raising this issue every week,” Tan recalls.
In 2020, he launched Brick, a platform that provides open finance APIs that enable companies to aggregate data. It connects financial institutions, businesses, and customers in Indonesia, allowing companies to access their users’ financial account data through a quick, automated, and integrated process.
Promoting financial inclusion
The benefits of having open finance APIs go beyond serving the needs of fintech businesses, says Tan, who also serves as Brick’s CEO. The average Indonesian citizen, he notes, will come out ahead too.
Much of the population in the archipelago remains unbanked, and roughly two-thirds of the country’s citizens don’t even own a bank account.
According to Tan, many Indonesians – especially the country’s informal workforce – still rely on cash or alternative financial accounts.
“A lot of mom and pop stores, for example, don’t have great bookkeeping records. They don’t bank all of the money they receive in a bank, and a lot of their business activity is done on a cash basis, so there are not many financial records,” he explains.
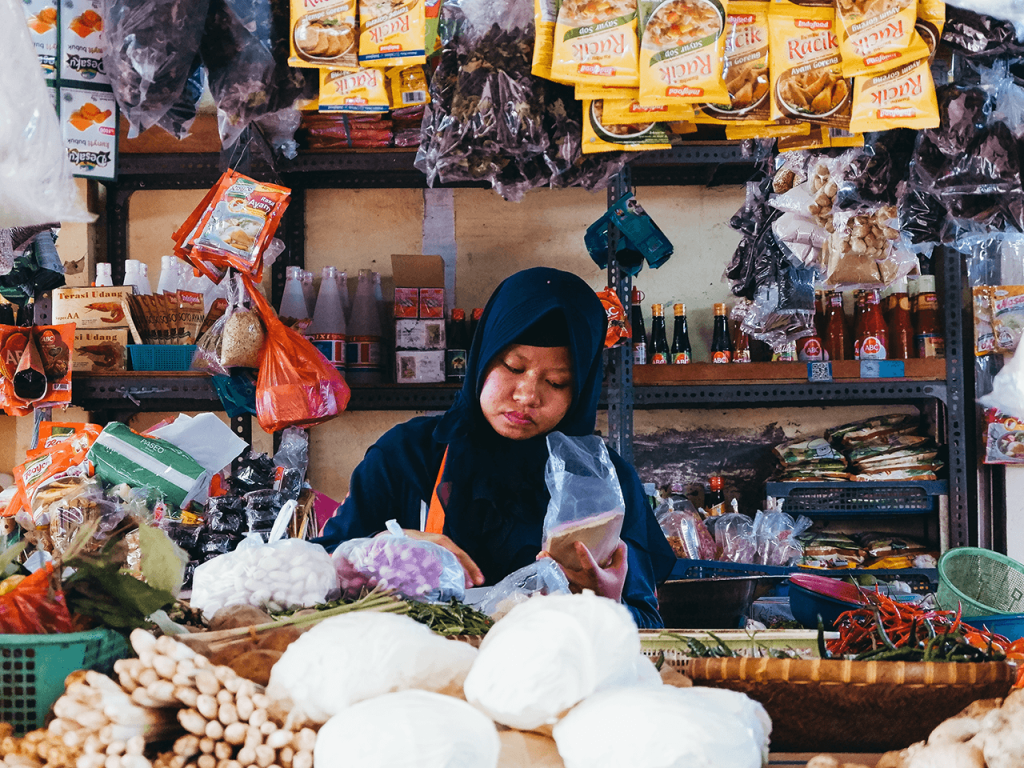
Photo credit: Devi Puspita Amartha Yahya via Unsplash
This lack of data makes it difficult for existing financial institutions to serve them.
Moreover, some of these institutions operate on a slow and aging infrastructure that makes it hard for these citizens to share their financial data even if they wanted to.
With Brick’s open finance APIs, however, customers can now easily and securely share whatever financial information they have with these institutions, streamlining the data gathering process at the same time.
Its APIs can also include financial data from informal financial accounts, such as those found in digital wallets or ecommerce accounts. That’s one step closer to financial inclusion in the country.
Laying the groundwork
With the goal to bridge the gap between Indonesians and financial services, Tan and his co-founders at Brick initially worked on several possible solutions.
One idea they eventually landed on was processing and digitally converting photos of physical documents to facilitate financial data collection.
This helps businesses streamline the onboarding process, which typically involves manually sorting customer documents. The whole process would often take a few days or up to a week, making the user experience less than ideal.
The solution would also allow these businesses to categorize the financial data gathered and draw greater insights.
By applying data science models and algorithms to these digitized financial data points, businesses can identify important information such as recurring income streams, payments, and where users spend their money.
Over time, Brick made improvements to the service by building a machine learning model to automate the financial data gathering and categorization process. This reduced the amount of manual work involved in building the required algorithms even further.
While the company’s early efforts were well-received by its initial pool of customers, they also exposed a challenge that the firm needed to overcome.
Even though businesses were happy to use Brick’s open finance APIs to automatically access its users’ financial account statements and other data, Tan says not all users were comfortable with the idea.
To solve this, Brick gave its customers the option to implement a semi-automated process. Instead of granting access to businesses directly, users could choose to upload documents manually, while keeping the processing workflow on the business’s end automated.
Developers and regulations first
The company has since expanded its arsenal of open finance APIs to include identity and financial account verification, as well as transaction information, employment data, and financial data collection. One of its latest releases is a disbursement API that allows tech companies in Indonesia to efficiently disburse money to bank accounts and digital wallets across the country.
Implementing the solution is simple for businesses – they need only to integrate Brick’s widget into a website or app.
The diverse range of applications and use cases has allowed the company to grow its client base to more than 50 customers since its founding last year.
What makes Brick stand out is that it focuses heavily on the developer experience, says Tan.
The company has endeavored to make the onboarding process for developers as smooth as possible by making its APIs easily accessible through developer-friendly documentation. Compare this to traditional sales processes where developers would have to book a demo with the API provider before they could even begin building on it.
With Brick, developers can sign up to get the API key directly and start using it without any human intervention from the company.
Brick’s strong emphasis on regulatory compliance has also come in handy, as it gives users the confidence that its services are stable and above board.
The firm is in close consultations with Bank Indonesia – the country’s central bank – in the area of open finance regulations. Through these consultations, Brick hopes to take part in a pilot project that would allow it to test out some of its more innovative ideas in a safe environment for open finance implementation.
Eventually, Tan sees Brick becoming almost like a “financial API supermarket” for Indonesia’s growing fintech market.
“Whenever anybody wants to launch a new fintech service or feature, I hope they will think of coming to us to pick the relevant APIs. [It would be as easy as] plug and play,” he says.
Brick is one of the leading fintech open finance API platforms in Indonesia and Southeast Asia, with API solutions for businesses to access and capitalize on important financial data.
To find out more about Brick, visit its website.
This content was produced by Tech in Asia Studios, which connects brands with Asia’s tech community. Learn more about partnering with Tech in Asia Studios.
Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.
Recommended reads
 SG minister highlights AI adoption pitfalls in SEA
 Australia to roll out trial program for CBDC
 How fintech firms can develop great products to stay ahead of the curve
 This Singapore company is turning the tide of plastic pollution at scale
 Bank of Thailand partners with 2C2P, others to launch CBDC trial
 For Binance, it’s sunny in stablecoin land
 SG crypto exchange Hodlnaut files for protection from creditors
 Binance’s big BUSD push heralds a stablecoin summer
 Indonesian regulator halts new crypto exchange registrations
 The Philippines pauses digital asset licenses for 3 years
Editing by Nathaniel Fetalvero and Jaclyn Tiu
(And yes, we’re serious about ethics and transparency. More information here.)



📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026