 Sumit Chakraberty · · 8 min read
11 young fintech startups playing with disruptive tech in India
Photo credit: Pexels.
A fintech transformation is under way in India. It began with the government working with tech evangelists to lay out the infrastructure: a biometrics-based Aadhaar ID for every citizen to enable authentication, and a unified payments interface (UPI) to simplify money transfer. Then, a withdrawal of cash from the economy gave a push to go digital.
The big players in this space, such as Alibaba-backed Paytm, were the first to see their traction take off in the wake of these developments. But now, we’re seeing new innovators emerge on the scene to ride the fintech wave. State governments and traditional institutions, too, seem eager to work with fintech startups. The path to scalable and sustainable businesses for these ventures is far from clear, but at least there appears to be broad consensus that fintech can bring efficiency, reduce costs, and have a multiplier effect on business and jobs.
Last week, Singapore’s Lattice80 – the world’s biggest fintech hub spanning 30,000 square feet – announced its first center abroad. This is coming up in Vizag on the east coast of India, where the state government has committed to support fintech adoption.
Earlier this month, entrepreneurs got together with banks, corporates, and government officials for the Fintegrate conclave in the Bombay Stock Exchange. It’s an initiative by Zone Startups India – a joint venture between the Bombay Stock Exchange and Canada’s Ryerson Futures, which has accelerators and a seed fund.
The highlight of the conclave was a demo by 10 emerging fintech startups chosen out of hundreds. They gave a glimpse into how innovators are using new technologies like artificial intelligence and building on the so-called India stack of Aadhaar and UPI. The panel of judges had senior executives from top banks like HDFC and ICICI, as well as corporates like IBM and Capgemini, and not just VCs and mentors. It shows a new interest in engaging with startups even if they are out to disrupt traditional systems.
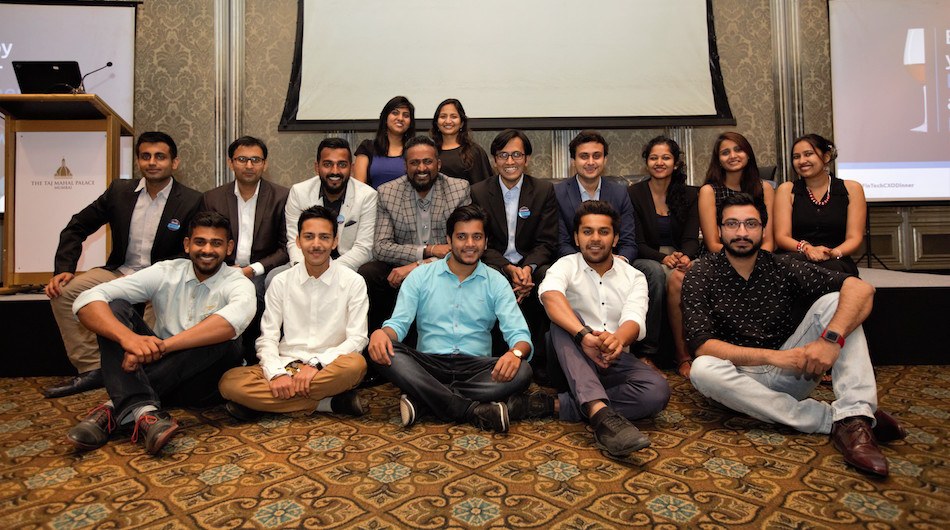
Meet 10 startups out to grab the fintech moment in India. Photo credit: Fintegrate.
Here are the ten potential disruptors:
Fingpay
Fingpay is a product of Indore-based Tapits. It uses Aadhaar ID and biometric authentication to let merchants accepts digital payments even from customers who don’t have a card or wallet.
Founder and CEO Pratyush Halen, who is from a business family in the tier-2 city of Indore in central India, points out that it took years for India’s leading digital wallet Paytm to get 100 million customers after burning cash on marketing and onboarding. “Here, within a year, we have equipped 780 million Aadhaar holders who can make payments with the swipe of a finger.”
The bank account linked with the Aadhaar ID is debited after the authentication. The merchant can buy the biometric reader from the Fingpay app for INR 2,000 (US$30).
The customer only shares a mobile number, which is mapped with their Aadhaar ID at the back end. For additional security, the fingerprint is also encrypted at the device-level itself, so that it can’t be misused in transit.
AnyTimeLoan
Hyderabad-based AnyTimeLoan provides short-term unsecured loans to needy people. Loans of INR 1,000 – 60,000 (US$15 – 900) are given for 1 to 90 days. “So it’s a niche product which doesn’t compete with personal loans of banks,” points out founder Keerthi Kumar Jain.
FRS Labs
DSYH
Sequretech
Perpule
S2Pay
vPhrase
Neuron
Beewise
Rockmetric





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.

📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026