 Peter Rothenberg · · 5 min read
Ebook: What you need to know to start a business in Japan
This is extracted from our Market Expansion ebook, which gives tips on expanding into many Asian countries. Scroll to the bottom to download it.
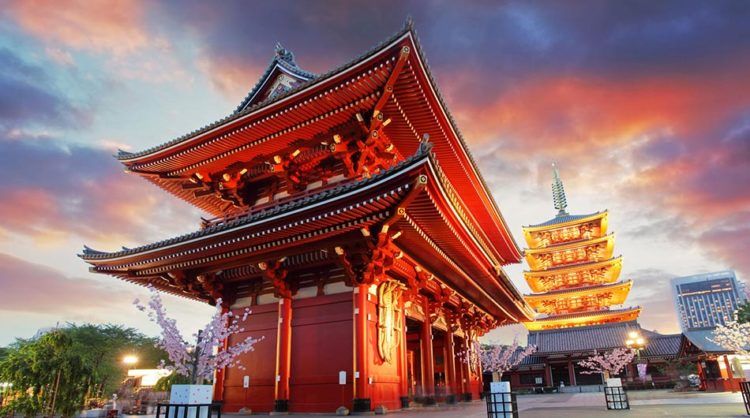
Photo credit: tomas1111 / 123RF.
The Japanese startup ecosystem is rather young. Most people peg it around 20 years old, having started during the dotcom boom. At that time, tech companies were concentrated in Shibuya, a district of Tokyo which was referred to as “Bit Valley” – a play on its Japanese meaning of “Bitter Valley.” While there may be less total capital available for startups in Japan compared to other countries, there is also less competition for that capital, making this a great time to start a business.
Up, up and away
In 2015, there was nearly US$1.5 billion invested in Japanese startups. The amount has been trending up since 2013 and finally surpassed the 2006 amount of US$1.4 billion. The median invested across 410 disclosed deals in 2015 was over US$1 million; close to double the 2014 average and the largest ever in Japan.
There are more accelerators, more co-working offices, and more venture capitalist popping up. Japan Venture Research lists 52 venture capital firms as of 2015. The median fund size is US$20 million and for the third year in a row the total amount of funds available to be deployed was over US$1 billion with the total of all funds reaching nearly US$2 billion in 2015. There are plenty of places to work. A 2014 study by Hokkaido University shows 365 co-working spaces (PDF) across the country.
Although startups are concentrated in larger metropolitan areas like Tokyo and Osaka, the government has been encouraging new business ventures and even created a special economic zone in Fukuoka with lower corporate tax. Foreign entrepreneurs can get advice and support from the Japan External Trade Organization (JETRO). Expected changes to visa laws next year will make it easier for foreigners to run a business. Fukuoka already has a special “Startup Visa” in place.
IPO friendly
The Japanese ecosystem is unique in that there have been a number of small market cap IPOs. Data from the Japan Exchange Group shows that most tech companies list in the junior section of Mothers, where the average IPO raised US$11 million and has a market capitalization of US$105 million. In 2015, of the 92 IPOs across all Japanese stock exchanges (excluding REITs and Tokyo Pro Market), over 50 percent were tech related.
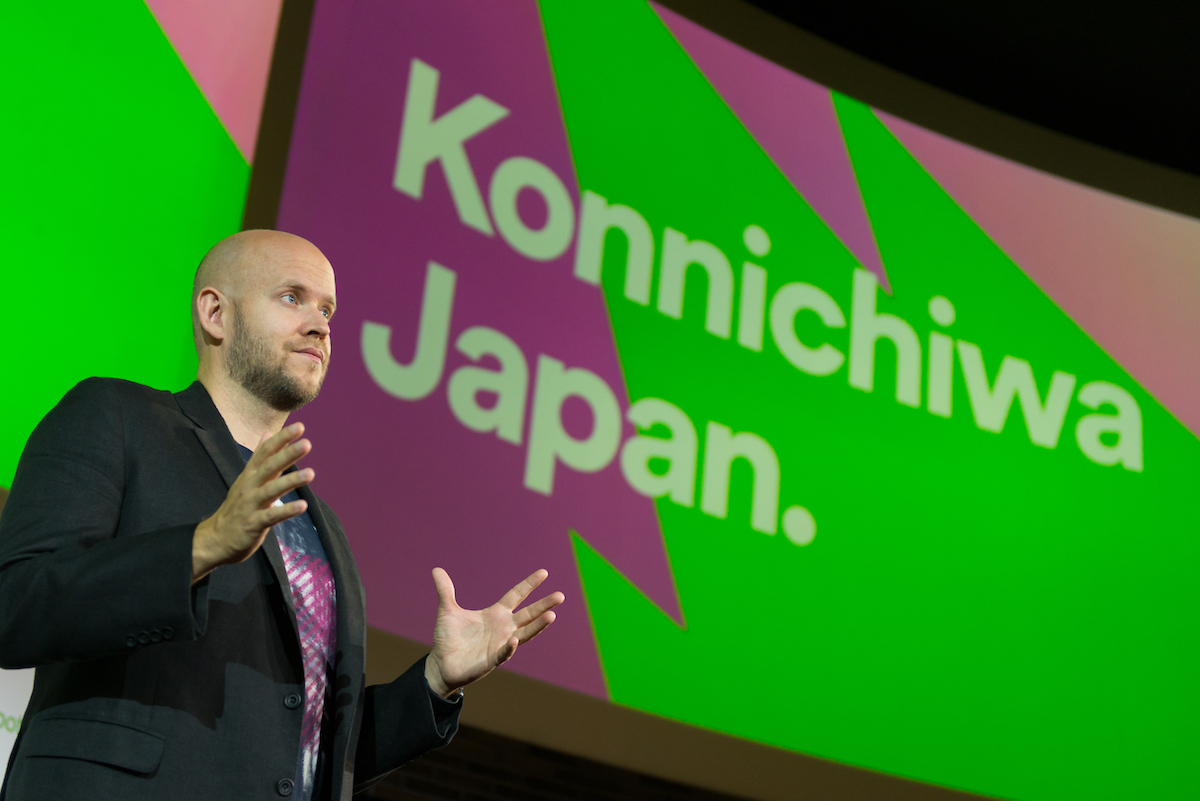
Spotify CEO Daniel Ek pictured in Tokyo at the startup’s Japan launch event. Photo credit: Spotify.
With recent large exits like gaming company Gumi in 2014 which raised US$450 million in its public offering, IPOs are starting to rev the ecosystem driving engine of angel investors who have money and business experience. This is much needed, as current estimates put the number of active angels in the country at only 20 to 30.
The US$1.3 billion raised by messaging app Line’s dual listing on the New York and Tokyo exchanges earlier this year is also hoped to bring renewed interested in startup acquisitions by large companies.
Trust
Japan often favors relationships over economics, so developing trust is vital. In 2006, a law which required companies to have at least US$100,000 in capital before incorporating was changed to make it possible to start a corporation with as little as one yen.
However, when dealing with large businesses, the US$100,000 amount is still one of the first checks done to judge a company’s trustworthiness. Partnerships are extremely important in Japan and having a big name as one of your clients can help lead to more deals. When selling to large corporations you should be aware that the person you are negotiating with may actually have no decision making power. They will often report to their superiors or the board who makes the final decision. Expect to meet your contact several times until they can explain the ins and outs of your business.
A new career





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.






📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026