 Daniel Tay · · 6 min read
This startup created a truly Asian solution for mobile payments, now claims largest client base in the region
To many of us in the tech world, owning a smartphone may seem to be a given – almost every other person we see around us owns one. A recent study conducted by Nielsen revealed that smartphone penetration in Asia Pacific has seen “exponential growth” over the past few years. In Southeast Asia, however, the numbers don’t appear to be too hot: Singapore tops the chart at 87 percent, followed by Malaysia (80 percent), Thailand (49 percent), Indonesia (23 percent), and lastly the Philippines at 15 percent.
On the other hand, looking at the absolute numbers involved tells a different story. Take Singapore and the Philippines as an example – while Singapore’s penetration rate of 87 percent comes out to about 4.5 million people, a mere 15 percent of the Philippines population crushes that number at 14.8 million. Put the total volume of smartphone owners in Southeast Asia together, and you’re looking at a vast market numbering in the billions – which is exactly what Chang Chew Soon, founder and CEO of Malaysia-based mobile card payment solution Soft Space, is counting on.
Let’s look at that number alongside the number of cards – whether they be ATM, credit, or debit cards – floating in the market now. “If you look at card penetration in Malaysia, we have about 20 million ATM cards out there right now,” Chang explains. “So if you put that together with the number of credit or debit cards floating in the market, I would say that almost every citizen in Malaysia should have a card to use for payments. And our Soft Space solution accepts a variety of cards, from ATM to Amex.”

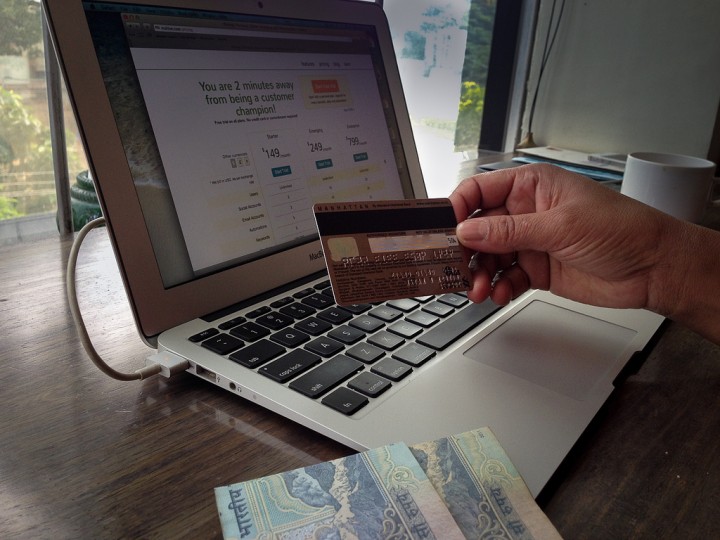
Soft Space’s core product is a mobile point of sale (mPOS) platform for card payments. This solution allows merchants to accept card payments through their mobile devices, at a price that is far cheaper than a traditional POS system would cost. A Soft Space card reader would cost about US$80, according to Chang. Because merchants would likely already own a smartphone, the overall cost of using their system is incredibly low.
Dominating the Asian market
Chang claims that Soft Space currently has the largest client base in Asia right now. “In Thailand alone, we’re looking at over US$1 billion in transactions,” he shares. “Meanwhile, we’ve just started our partnership with CIMB bank in Malaysia, and already we’ve shipped out 10,000 card readers to them.” CIMB bank is one of three clients they have in Malaysia – another is Hong Leong Bank and the third will be announced later this year.
In the short span of 17 months since launching in January 2013, 10 banks across Asia Pacific have already signed up, with several others currently in talks with them. The Malaysian company’s customer base is, however, not just limited to Asia – they are also in Australia and New Zealand as well.
What is their secret to conquering the Asian marketplace, especially since other solutions such as the US-based Square were in the market long before Soft Space entered?
Chang says they were able to beat their competitors from the West due to two reasons. Firstly, the team paid particular attention to payment behavior in Asia. “If you built a payment system designed to run in the West, and transplanted it in its entirety to Asia, it’s definitely going to tank,” he explains. “We capitalized on our unique understanding of the Asian market to grow exponentially here.”
Secondly, Soft Space has the honor of being the first payment solution in Asia to receive full EMV accreditation, and as such, were also the first in Asia to launch an mPOS solution as well. EMV – which stands for Europay, MasterCard and Visa – is a global security standard for chip card technology, and it enables chip cards to be accepted anywhere in the world. Being EMV accredited demonstrates trustworthiness to financial institutions, and of course, allows merchants to accept card payments on their smart devices.
Chang was proud to share that Soft Space was able to get certified within three months. In comparison, it took Swedish-based card payments platform iZettle 18 months. “I guess we were lucky,” joked Chang. “But on a more serious note, I think it was largely due to the fact that a lot of our guys came from the payment industry, so we are very used to building apps and interfaces with bank solutions, which definitely helped us a lot.”
With these advantages, the team was able to deploy their solution in banks across Asia before other competitors could even enter. The more banks they got on board, the more matured their system became, which subsequently made it even easier for them to pitch to other banks.
An initially rocky path
The future of payments





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.






📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026