- Insights This article was written by a TIA community member. Insights pieces undergo the same rigorous editorial process that newsroom-produced articles have.
 Jun Yan · · 5 min read
As Chinese tech arrives in pieces, what should SEA firms own?
In June, Nvidia unveiled a reference humanoid robot design. Powered by the US-based chipmaker’s own compute and software, it pairs a Unitree H2 Plus body from China with tactile hands from Singapore-based company Sharpa.
The boundaries blur further once ownership and supply relationships are factored in: Hesai, the Chinese lidar firm, disclosed that its co-founders still hold a majority of the voting rights in Sharpa. Hesai also supplies Sharpa with actuators, which turn control signals – like electricity or air – into physical movements.
Image credit: Ulla
If you’re wondering which country’s tech was showcased at the Nvidia launch, there is no clear answer. And for Southeast Asian companies, there’s an even bigger question: If the body, hands, compute, software, equity, and supply chain can come from elsewhere, then what do they actually need to own?
Half of the founders, investors, and employees surveyed for Tech in Asia’s 2025 conference report consider China as the blueprint for Southeast Asia’s tech ecosystem. For much of the last decade, the reference was usually an individual company – like Didi, PDD, or ByteDance – and its product, distribution, and monetization are studied as a whole.
See also: The startups behind Southeast Asia’s physical AI push
Now models, robot platforms, components, and compute are increasingly available separately. If much of the underlying tech can be bought, then the harder choice for Southeast Asian firms is what not to outsource.
The decision, however, is not between building and buying. Instead, it lies in the company’s ability to carry over what it learns from one deployment to the next, and whether that holds even when the implementation crosses a border.
What SEA firms are choosing to keep
Grab, the Southeast Asian super app, has been making versions of that choice for years. Its fraud models are typically built regionally, then adjusted by country teams to local regulations, needs, and data.
GrabMaps crossed a different line: When outside providers could not capture enough of Southeast Asia’s local detail, Grab built its own mapping capability. The question was not simply whether to build or buy, but where the company needed to learn more.
AI and robotics are moving that line again. Vietnam’s VNG, for instance, has trained its own Vietnamese-language foundation models, including the 13-billion-parameter KiLM.
VNG’s GreenNode cloud unit launched the 14-billion-parameter GreenMind in 2025, while its broader stack can work with its own and third-party models. GreenNode serves more than 1,000 enterprise customers, with revenue rising 57% to roughly US$29 million and net revenue retention reaching 123% last year. It operates six availability zones across Vietnam and Bangkok.
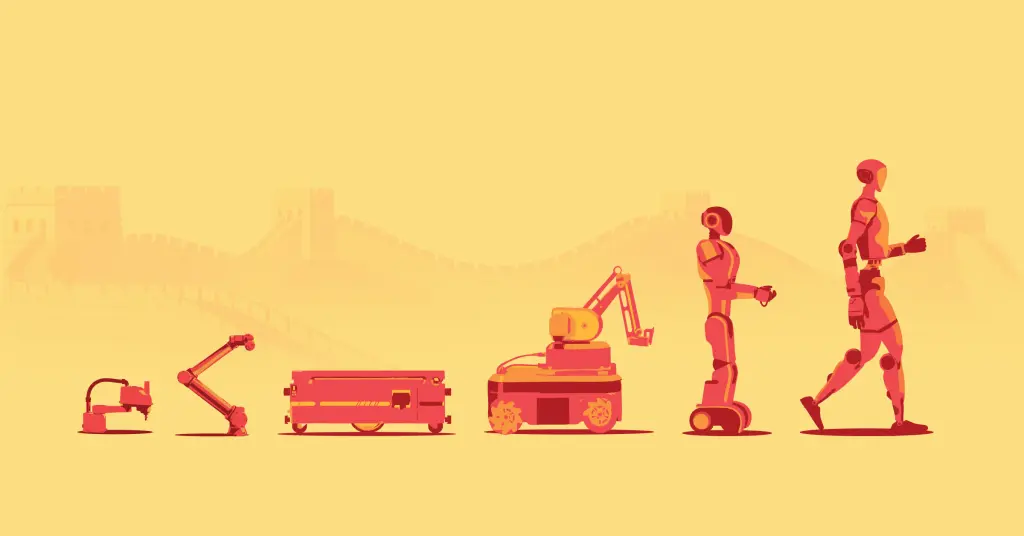
Image credit: Arsal Ysfin
Where the real test is





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.




📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026