- Premium Content It takes our newsroom weeks - if not months - to investigate and produce stories for our premium content. You can’t find them anywhere else.
 Simon Huang · · 6 min read
6 surprises from the reveal of Grab’s jealously guarded financials
Grab’s announcement yesterday that it was going public in the US by way of a special purpose acquisition company (SPAC) was expected. Tech in Asia had raised this possibility back in January.
The company’s investor presentation, which revealed Grab’s previously closely guarded financials, did contain a number of surprises.
Here’s what caught our attention.
1. Delivery – not mobility – is now Grab’s largest segment
Grab has four main business segments: delivery, mobility, financial services, and enterprise and others.
Its first products, GrabCar and GrabBike, are in the mobility segment. And for many Southeast Asians, these ride-hailing services cemented their first impression of Grab as a local alternative to Uber.
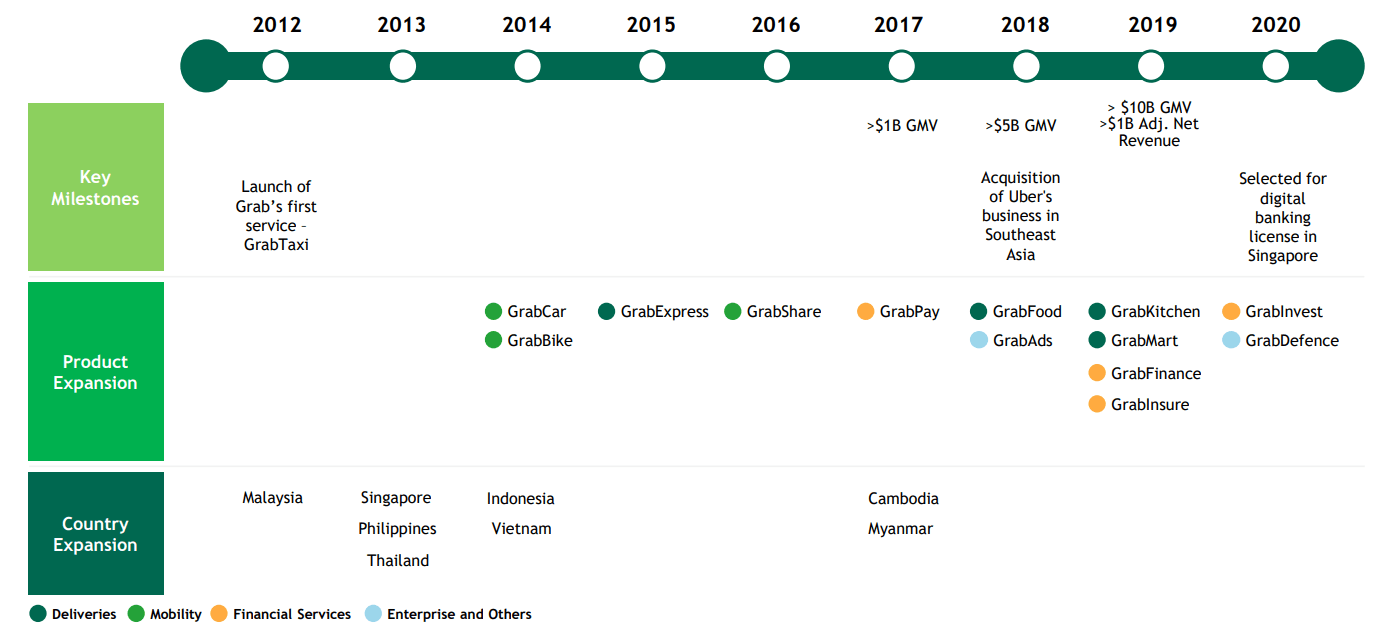
Image credit: Grab
In 2018, mobility dominated Grab’s business, accounting for 80% of its consolidated revenue. However, by the end of 2020, mobility’s share had fallen to 31%.
Delivery, which contributed to 49% of total revenue in 2020, is now the biggest segment. The speed and magnitude of this change is evident from the chart below.
The Covid-19 pandemic forced people to spend more time at home. Consequently, this reduced demand for transport, and Grab’s mobility revenue fell by 17% in 2020.
However, this drop also drove up demand for delivery, with users booking riders to move everything from food to parcels. As a result, revenue for delivery surged by 300% during the same period.
But this doesn’t mean mobility has become less important to Grab. In fact, it’s currently the company’s only profitable segment: Its 2020 EBITDA (earnings before interest, taxes, depreciation and amortization) was US$300 million.
Grab points out that “structural reasons” underpin the profitability of its mobility arm. Its driver-partners can choose what they prefer to transport – people, parcels, or groceries. Many pick a combination of these options.
2. Grab is an ecommerce play
3. Faster growth projected for delivery than financial services
4. The 47% EBITDA loss margin
5. A three-year lock-up of Altimeter’s sponsor promote shares
6. Loftier-than-expected valuation
Stay ahead in Asia’s tech landscape
This is premium content. Subscribe to read the full story.
We finally got a closer look at Grab’s financials this week, and here are six things that surprised us.
We know this is not ideal. ⌛ Sign up in 20 seconds. Cancel anytime.
Our subscriber community includes professionals from these companies:





📅 Upcoming Events
30-31 March 2027
Upskill Fest