- Insights This article was written by a TIA community member. Insights pieces undergo the same rigorous editorial process that newsroom-produced articles have.
 Jaclyn Tiu · · 4 min read
Why are Grab, AirAsia, and other big names moving into fintech?
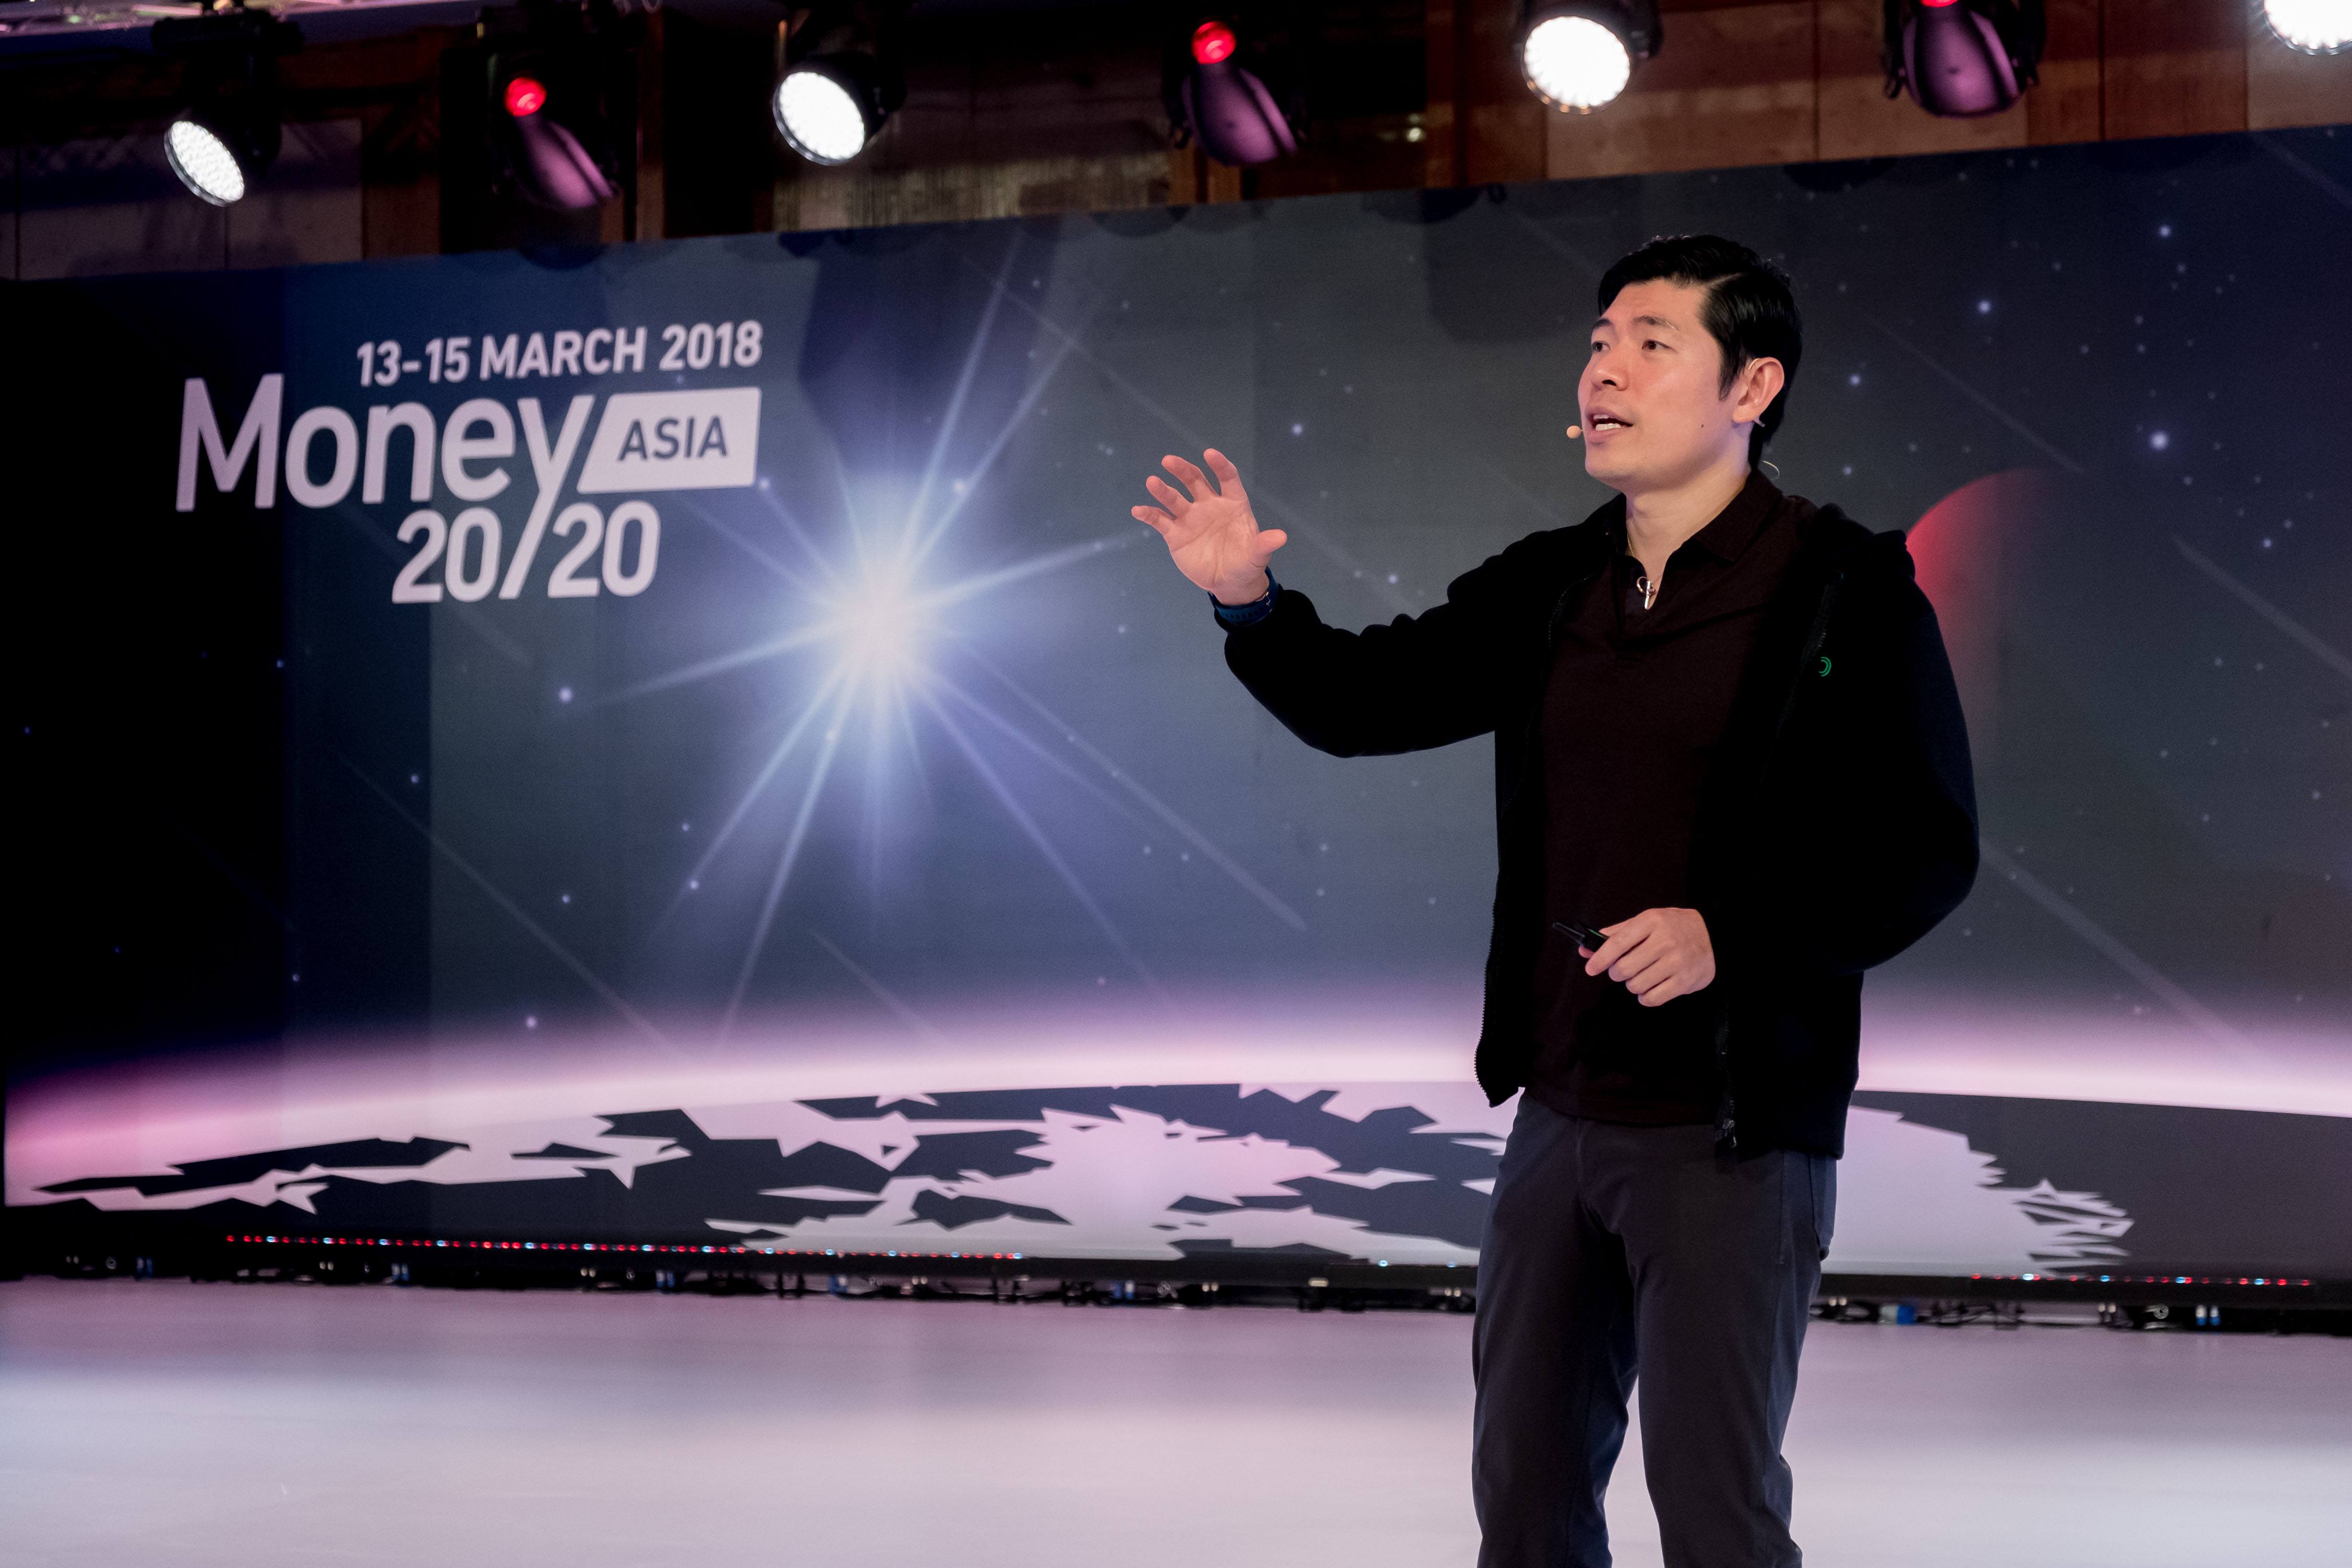
Grab co-founder and CEO Anthony Tan at Money 20/20 Asia in Singapore / Photo credit: Grab
Discuss features short but strong and insightful opinions on interesting startup, entrepreneurship, and tech topics. Got a topic or question to suggest? Drop us an email or leave a comment.
Just last week, Grab announced its next move: a financial services venture. AirAsia similarly announced a new digital payments platform, BigPay.
Add that to Go-Pay, WeChat Pay, Sea Group’s AirPay, and we have a host of digital payment platforms from companies that didn’t originally start out in fintech.
We asked two experts why this is the case.
Editor’s note: Answers have been edited for clarity.
Lawrence Cheok, senior research manager at IDC
In the short term, it’s about customer acquisition and changing consumer behavior. Once early adopters are well penetrated, market expansion involves enticing early/late majority segments, which in SEA includes the unbanked segments.
One way to do this is to enable consumers to convert cash into digital forms. This typically involves leveraging physical points of sales to top up wallet credits/balances. Examples such as Go-Jek Pay and AirPay point to this trend. It is only when late followers are able to make digital payments can tech companies sell to them.
A single payment platform unified with complementary services would facilitate cross-selling. Billing, ticketing, gaming, and O2O services increase the “stickiness” of digital platforms among consumers. For businesses, it can reduce acquisition cost and improve loyalty. In segments where products/services are highly commoditized (e.g. ride-sharing), the service synergy plays an important role in driving loyalty and possibly offset aggressive promotions.
To this end, digital platforms have rolled out loyalty-like programs such as credit points, which consumers can use across a range of services accessible from one single platform. One example is GrabPay’s credits which can be used for taxi rides or at partnering businesses.
In the mid to long term, these digital platforms can leverage data across its ecosystem to drive innovation. As we’ve seen with AliPay and Ant Financial, financial products such as Sesame Credit arise from consumer data which Alibaba’s ecommerce platforms generate. The Grab Financial launch seems in line with this strategy. If you look at China in its developing years and SEA today, there are similarities in the opportunities these unbanked segments present and how companies are addressing it.
Let’s discuss





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.