- Premium Content It takes our newsroom weeks - if not months - to investigate and produce stories for our premium content. You can’t find them anywhere else.
 Melissa Goh · · 7 min read
Founders fume over Malaysian VC’s term sheet
A term sheet offered by First Frontier Borneo Capital (FFBC) has drawn skepticism, with its conditions seen to disadvantage the firms it is meant to support.
The investment at stake is from the government-backed Sarawak AgriFoodTech Sustainability Impact Fund, of which FFBC is a VC partner.
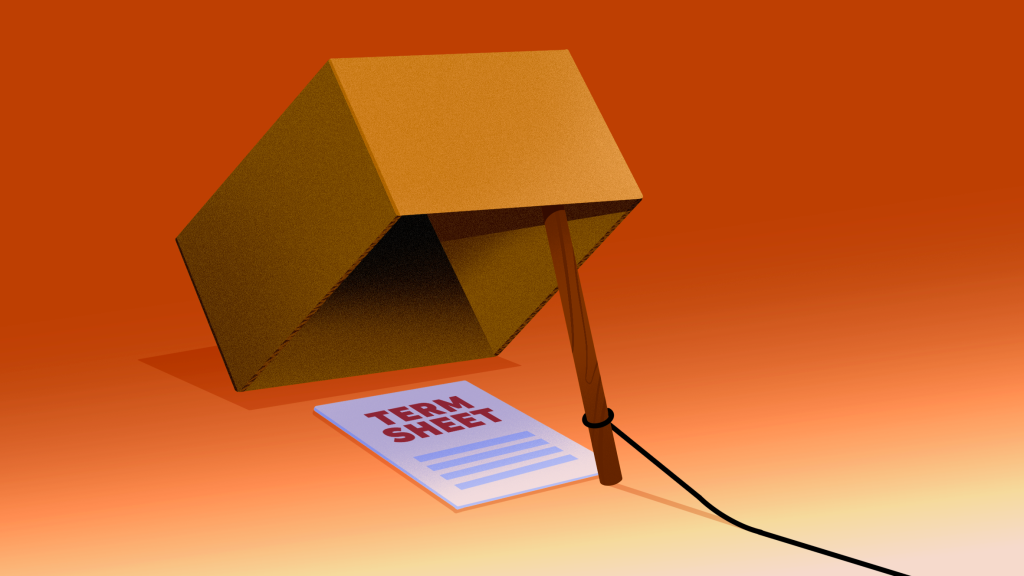
Image credit: Timmy Loen
Launched in August 2024, the 100 million ringgit (US$22.6 million) fund is a collaboration between the Sarawak government and VC firm First Frontier Ventures, the sole shareholder in FFBC, as per filings with the Companies Commission of Malaysia.
Of the total, the Sarawak government has committed half, with the balance matched by private investors.
However, certain terms in the document – especially in relation to liquidation preferences and exit mechanisms – appear extreme, according to a VC investor, a lawyer, and two Malaysia-based founders interviewed by Tech in Asia. (Editor’s note: The founders interviewed for this story did not receive the questionable term sheet. They shared their views on some of the terms being offered.)
While a term sheet is non-binding and not definitive, it outlines the key terms parties expect to agree to in a legally binding agreement.
The unfavorable deal terms have repercussions beyond this fund. They offer a peek into some of the frustrations founders face in a country where funding support is lacking – particularly in later stages – and investors lack experience investing in startups.
And while the country’s state funds are also looking to boost their investment in local startups, offering the wrong terms may end up putting the founders at a disadvantage in the future.
FFBC declined to comment when contacted by Tech in Asia.
When de-risking adds risk
One of the terms mandates that the investee company complete a follow-on fundraising round with at least double its initial valuation within three years of the investment.
Should the startup raise further funding, the backer can exercise a put option, which gives them the right but not the obligation to sell its shares to the incoming investor.
Clauses like this present several problems. One, it could turn away future backers.
“What investor is going to come in when a company is young and say, sure, I’ll put in [a few] million ringgit, and [find out] that it’s going in solely to pay off an existing investor?” Kevin Brockland, founder and managing partner of early-stage VC firm Indelible Ventures, tells Tech in Asia.
Other difficult terms
Compensation for rejection?
All about downside protection
Stay ahead in Asia’s tech landscape
This is premium content. Subscribe to read the full story.
The VC has been offering terms that some find onerous. We look at what these terms are and how they might hurt startups.
We know this is not ideal. ⌛ Sign up in 20 seconds. Cancel anytime.
Our subscriber community includes professionals from these companies:





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.

📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026