Gilang Kharisma · · 3 min read
ShopeePay CEO on BNPL: why relying on late fees will fail
This article summarizes an episode of Fintech Fireside Asia’s video series featuring Alain Yee, CEO of ShopeePay Malaysia.
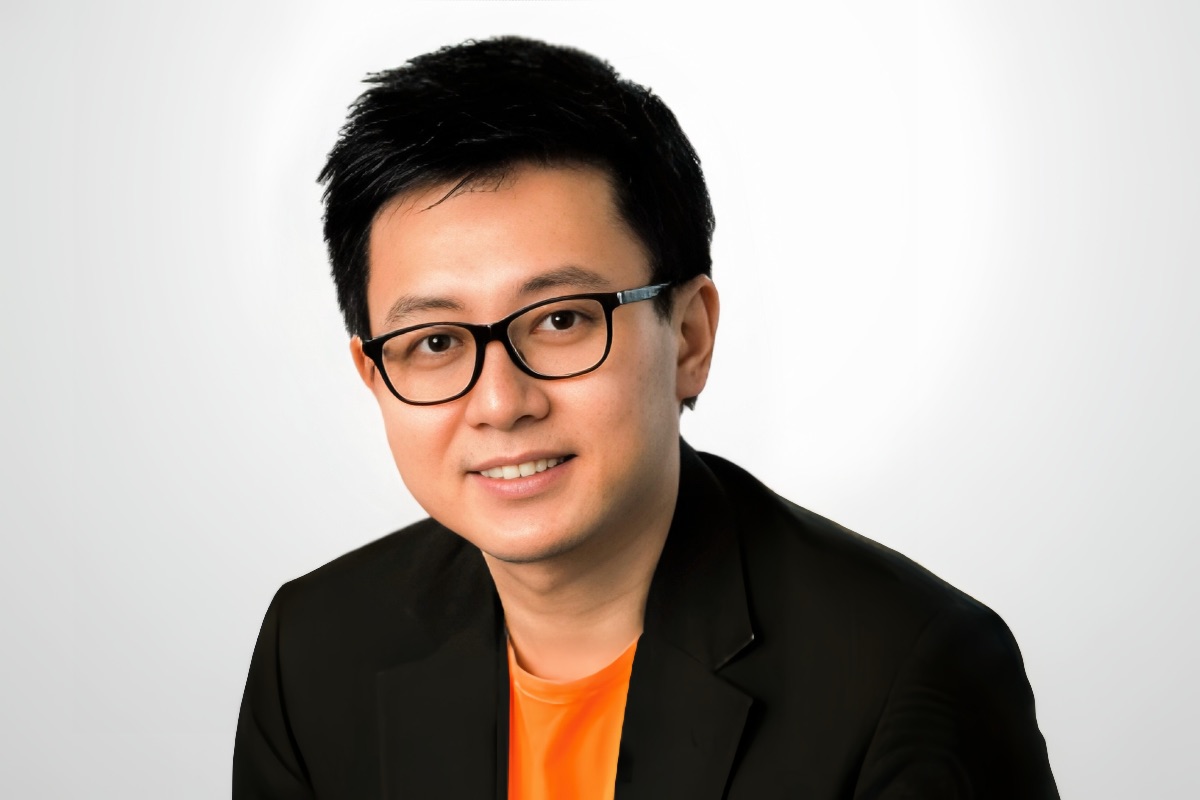
Photo credit: ShopeePay
The survival of a Buy Now, Pay Later (BNPL) business does not depend on making money from late fees. Instead, it relies on freezing customer accounts at the first missed payment to stop debt from growing.
Alain Yee, CEO of ShopeePay Malaysia, explains that independent digital lenders are at a disadvantage compared to large ecommerce platforms, which use their existing shoppers to lower the cost of finding new users.
To win in this market, companies must buy out competitors to reach more people, use strict rules to prevent unpaid debt, and only offer financial services to solve real checkout problems.
Ecosystem dominance crushes standalone lenders
Independent BNPL providers operate with a structural disadvantage, driving consolidation. As Yee puts it, “those left have an ecosystem or are close to an ecosystem.”
Mergers now transform digital lenders into bridges that connect shopping spaces:
- Acquisition as distribution: Grab acquired Atome for US$1.49 billion to infiltrate store networks outside its application.
- Ecosystem integration: Accessing a network of partner merchants carries more value than the loan balances of a company.
- Cross-platform reach: Mergers transform digital lenders into bridges that connect shopping spaces.
Product mechanics neutralize borrower delinquency
Once distribution is secured, operators must manage individual borrower risk. Lenders deploy strict product mechanics to prevent vulnerable shoppers from accumulating debt:
- Freeze accounts immediately. The SPayLater system locks a user profile after a missed payment.
- Eliminate compounding interest. Shoppers incur a 10 ringgit fee to unlock their account only after clearing the outstanding balance.
- Cap initial exposure. Providers mitigate risk among the 70% of users lacking traditional credit by enforcing 200 ringgit limits.
- Monitor aggregate spikes. Macro statistics hide concentrated risks, as unpaid BNPL balances surged from 1.1 billion ringgit to 4.9 billion ringgit despite representing just 0.3% of household debt.
As Yee puts it, “there’s no way to make money from overdue [balances], so there’s no interest in extending credit to people who cannot afford it.”
Late entrants must target visible friction
This approach to debt management mirrors ShopeePay’s strategy for product expansion, which relies on solving transaction bottlenecks rather than pursuing user acquisition:
- Launch products to rescue transactions during midnight sale server crashes.
- Convert online shopping traffic rather than acquiring new financial users.
- Adopt QR code systems to integrate with store merchants.
- Restrict loan products to productive uses like financing motorcycle transportation.
By pinpointing system failures instead of chasing user growth, companies ensure that every financial product serves a functional purpose. Sustainable digital lending requires abandoning predatory fee models in favor of credit caps and platform integration to eliminate transactional friction.
Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.