- Premium Content It takes our newsroom weeks - if not months - to investigate and produce stories for our premium content. You can’t find them anywhere else.
 Miguel Cordon · · 5 min read
Beyond BNPL: How BillEase turned and sustained a profit
At face value, it may seem that the cards have been stacked against buy now, pay later players lately.
Funding into BNPL firms has dropped from the heydays of 2020, and more users have fallen behind on their payments.
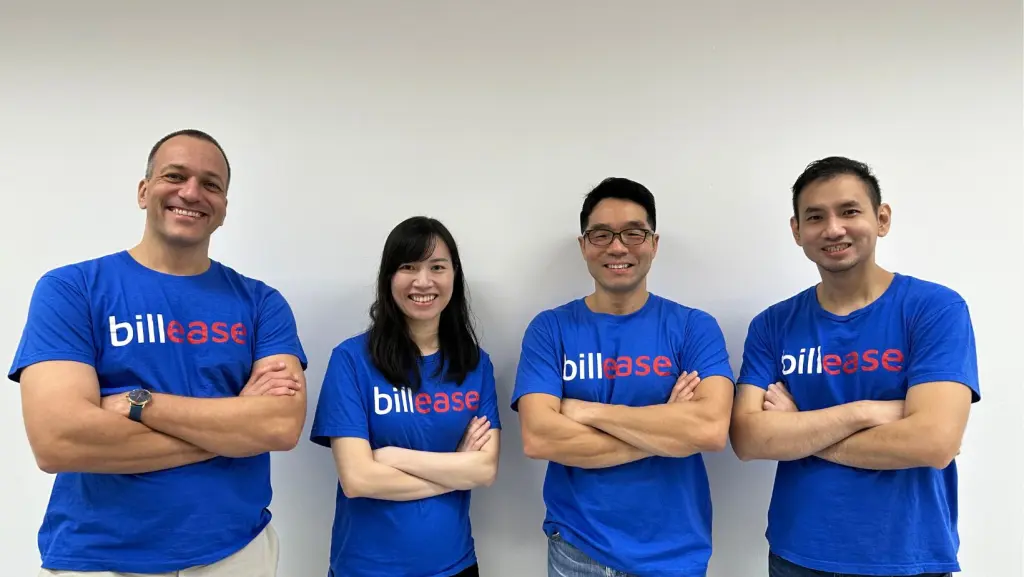
Photo credit: BillEase
Globally, few BNPL players are profitable, due to a combination of high credit losses and stiff competition – coming even from traditional banks. Many BNPL firms have ceased operations as well.
Philippines-based BillEase, however, has been in the black since 2023. This can partly be attributed to the breadth of credit and payment services it offers.
Unlike firms like Atome, which offers a physical credit card in the country, BillEase offers an ecosystem of products: In addition to installment payments, it also offers cash loans, e-wallet and mobile data top-ups, and bill payments.
BillEase CEO and co-founder Georg Steiger tells Tech in Asia that the two firms aren’t direct competitors, with both targeting a slightly different segment and use case.
Looking at the two companies’ credit limits – US$3,590 for Atome and US$720 for BillEase – the latter focuses on smaller, everyday payments, while the former gives room for users to purchase higher-ticket items.
Measured growth
While ShopBack closed down its BNPL business and Atome exited Vietnam in the past two years, BillEase grew its revenue by 51% year on year in 2024, driven by a 62% increase in interest income.
The company’s profit before taxes also rose by 50% in 2024.
Steiger notes that the revenue growth can be attributed to repeat customers and a push into offline transactions. In May 2024, the company said it had around 1.3 million users.
He’s forecasting a similar revenue growth rate for 2025.
BillEase’s biggest revenue driver is interest from cash loans, Steiger shares. It also earns revenue from its BNPL product and from commissions on transactions done through its app.
The company’s allowances for expected credit losses on loans grew from US$28.5 million in 2023 to US$37 million in 2024, which Steiger says have increased in tandem with its loan book.
A rising tide lifts all boats
Banking on offline retail
Building a US$300 million loan book
Stay ahead in Asia’s tech landscape
This is premium content. Subscribe to read the full story.
We explore how BillEase maintained its profitability in a challenging BNPL space and what it’s doing differently from the competition.
We know this is not ideal. ⌛ Sign up in 20 seconds. Cancel anytime.
Our subscriber community includes professionals from these companies:





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.