Kylee McIntyre · · 4 min read
How these Amazon and Xiaomi alums are helping the unbanked with blockchain
If you want a loan from a financial institution, you’ll probably need to sign off on a credit check – a look at your personal loan history – to go along with it. Credit checks are far from comprehensive, though. Chances are, someone with little to no loan history – or banking history, for that matter – won’t get approved, especially if that loan is large, say like a loan you need to start a business.
“A lot of the traditional models are not applicable to onboard those people into financial systems,” says Sarah Zhang, co-founder of Singapore-based Points.
Not to mention that the agencies traditionally used to run credit checks are prone to data leaks. Remember the Equifax breach last year?
“You need to have a much better infrastructure that doesn’t ask to expose people’s data,” explains Zhang.
That’s where Points – also called PTS – picks up the slack. Founded last year, the blockchain-powered startup uses AI and big data to assess factors like an individual’s occupation, bill payments, and shopping activities to calculate a credit score.
PTS raised US$8 million in seed funding this year. Contributors included Danhua Capital, Ceyuan Ventures, the Ontology Foundation, and Zhong Cheng Xin Credit Technology, China’s first nationwide credit rating agency.
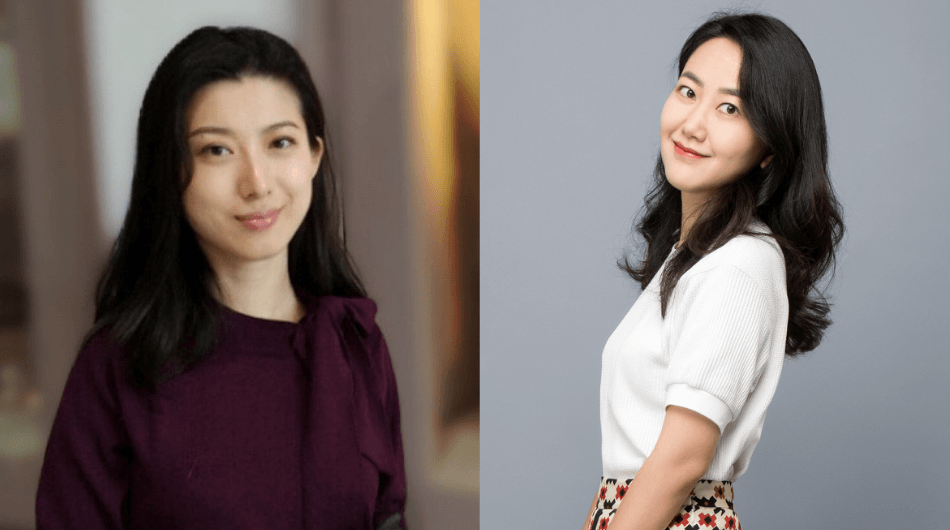
Co-founders Kate Shen and Sarah Zhang / Photo credit: Points
The blockchain answer
Zhang served as chair for Beijing-based blockchain talent platform dCamp, chief operating officer and senior director of Segway Robotics, and senior product manager at Amazon. A Harvard Business School graduate, She discovered blockchain while working in Silicon Valley in 2014, while she was a growth hacker for Draper University, the entrepreneurship school founded by venture capitalist Tim Draper.
“I thought it [blockchain] was an interesting idea, but the question kept coming back to me: what is the actual use case?” Zhang tells Tech in Asia. After puzzling over how to apply blockchain for a few years, she came to the conclusion that finance was a place where she could make an impact.
PTS faces competition from a lot of fintech startups trying to close the gap left by the credit industry. In May, Singapore-based Helicap, which uses peer-to-peer lending to assist loan-seeking small and medium-sized enterprises (SMEs), raised US$25 million in funding in May this year. In China, Tencent tried out Tencent Credit, a credit and microloan service in January. Other blockchain startups such as Colendi, Inviou, and Bloom also focus on addressing this issue, mostly for SMEs.
PTS, however, hopes that more individuals can use its platform, including those who are unbanked outside of China, in countries like Indonesia where it hopes to expand.
Points of contention
A big leg-up that PTS has is that it doesn’t actually store customers’ data. Traditionally, banks need to upload borrower profiles as part of the vetting process. Not only does this approach takes up time and data storage space, but the stored info is also vulnerable to hacks.
PTS’ protocol is built on top of Ontology, a public blockchain project and distributed trust collaboration platform. A user can submit their information to the protocol, which will calculate a credit score based on that input as well as data from credit bureaus that PTS has partnered with. The protocol acts like a secured highway, so it only approves or denies an application based on the credit score – it does not actually store the information. This limits the chance of a security breach during the calculation process.
Data – getting and safeguarding it – remains the company’s biggest challenge. “The sheer amount of data input is huge – 80 kinds of variables from 500 million consumers,” Zhang says. Even if someone did attack the system, the blockchain encryption keeps hackers from deciphering what they’ve found.
Key use cases





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.