- Premium Content It takes our newsroom weeks - if not months - to investigate and produce stories for our premium content. You can’t find them anywhere else.
 Melissa Goh · · 6 min read
SG digibank GXS trails Trust in adoption as deposit cap hampers growth
In Singapore’s tightly contested digital banking market, gaining an edge over the competition is no easy feat.
GXS Bank, the digital bank backed by Grab and telecommunications major Singtel, was launched just nine months ago. But it is already approaching the limits of how much it can grow – at least in retail deposits.
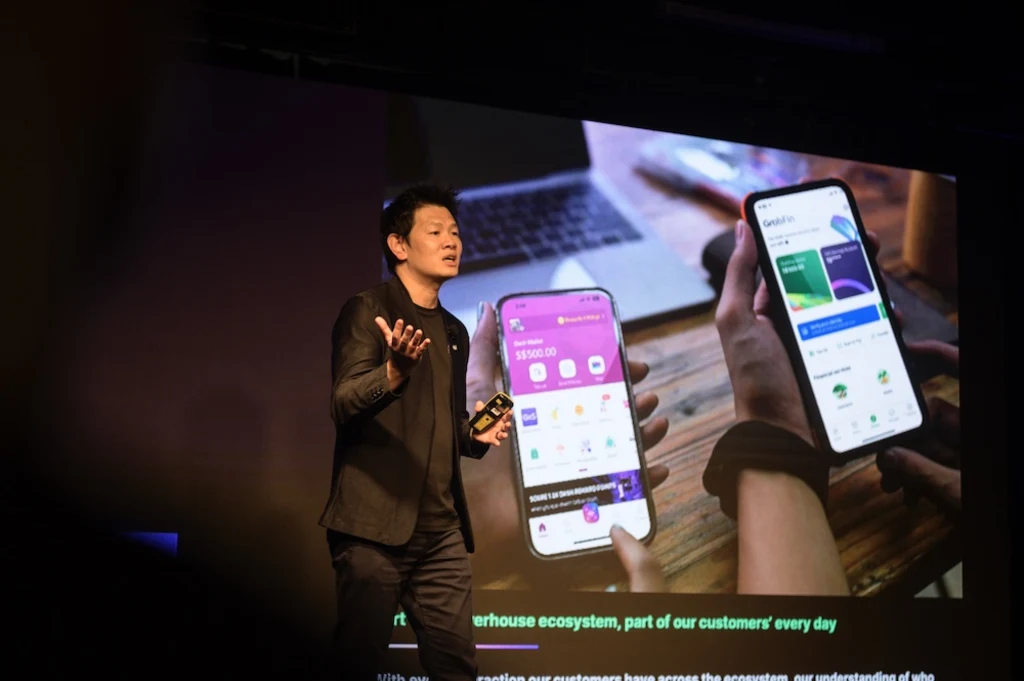
GXS Bank CEO Charles Wong / Photo credit: GXS Bank
In Singapore, digital full banks can accept up to a maximum of S$50 million (US$37.5 million) in deposits in their initial phase of operations. The limits, put in place by the city-state’s banking regulator – the Monetary Authority of Singapore (MAS) – among other business restrictions, are meant to minimize risks to retail depositors by limiting their exposure to new operators without a track record in banking.
GXS Bank is fast approaching that magic number. As such, despite the overwhelming response it has received, the digital bank is taking a pause on accepting new customers for its invitation-only savings accounts, CEO Charles Wong said at a press event last week.
Without being able to expand its anchor savings product, GXS will have to rely on credit or investment products to grow its user and revenue base until the MAS approves the increase in limits.
This explains the timeliness of its first credit product, which was launched last week: the FlexiLoan. At an interest rate of 3.8% per annum, FlexiLoan is on par with industry players like DBS Bank and UOB Bank, whose rates on comparable personal loan products start from 3.88% and 3.77% per annum, respectively.
As its name suggests, the product is flexible by design and can be customized down to its loan tenure (two months to five years), repayment date (to coincide with payday), and whether early repayments are made (no repayment fees). Loans can also be granted and disbursed via the GXS app in under three minutes.
More importantly, FlexiLoan is available to individuals in Singapore as long as they meet the eligibility criteria – citizens or permanent residents aged between 21 and 65 years with a minimum annual income of S$20,000 (around US$15,000) – even if they don’t have a GXS bank account.
Same same, but different
Meanwhile, rival Trust Bank operates under shareholder Standard Chartered Bank’s full bank license and isn’t subject to a deposit cap. Its other shareholder is FairPrice Group, Singapore’s largest supermarket retailer.
As it was established outside of the digital bank framework, Trust is not subject to its requirements, including the MAS’ phased process and other business and deposit restrictions.
It has been off to a roaring start.
Using carrots like free rice and breakfast sets to encourage sign-ups, Trust amassed more than 500,000 active customers within seven months after its launch, CEO Dwaipayan Sadhu tells Tech in Asia.
According to a third-party industry estimate, Trust has close to 60x more monthly active users than GXS as of March – even though they launched a day apart.
‘Close to zero’ customer acquisition costs
Playing the long game
Stay ahead in Asia’s tech landscape
This is premium content. Subscribe to read the full story.
Trust has close to 60x more monthly active users than GXS, according to industry estimates, even though they launched a day apart.
We know this is not ideal. ⌛ Sign up in 20 seconds. Cancel anytime.
Our subscriber community includes professionals from these companies:





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.

📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026