Steven Millward · · 6 min read
Inside Jack Ma’s playbook for Ant Financial’s global expansion
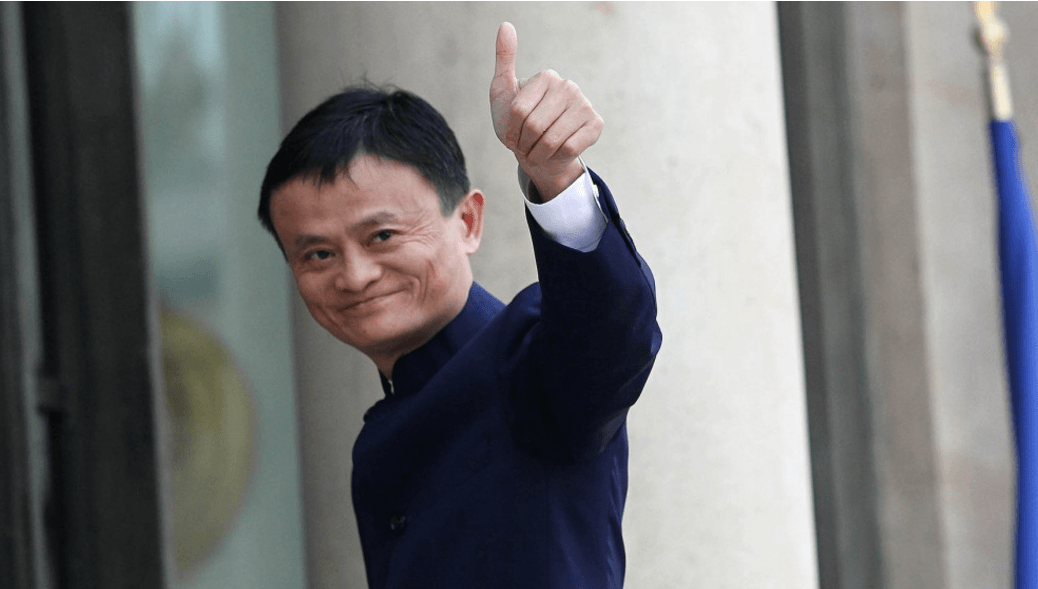
Ants in his pants: Alibaba and Ant Financial founder Jack Ma, 52, is China’s richest tech boss but he isn’t slowing down. Photo credit: Alibaba.
Jack Ma has built up not one but two tech giants. Alongside his US$250 billion Alibaba empire there’s Ant Financial, maker of China’s top mobile wallet app.
Valued at an estimated US$60 billion ahead of a possible IPO this year, Ant Financial is now on a streak of overseas deals as the firm takes its fintech services into new markets.
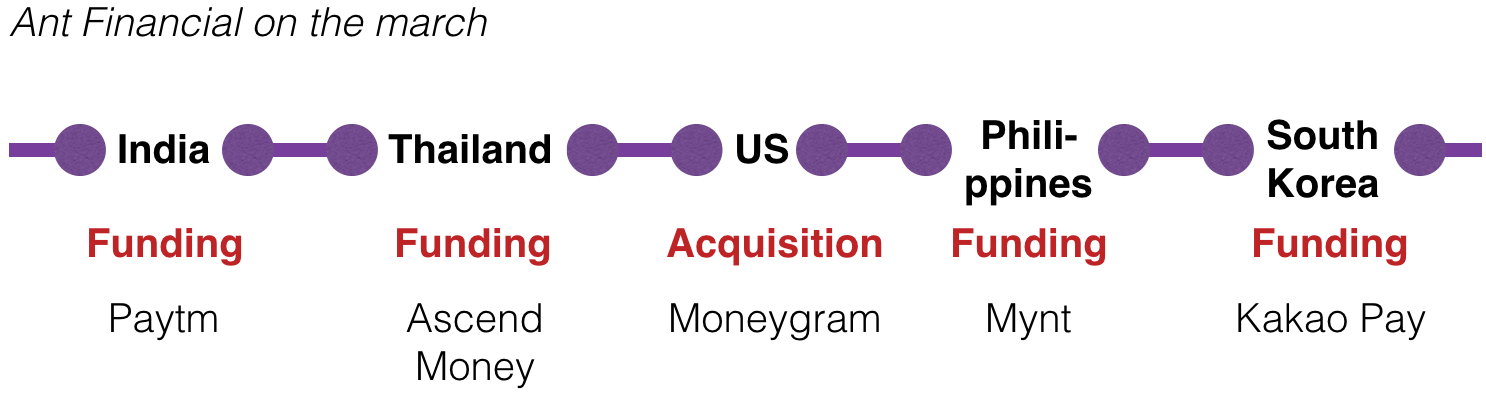
From those moves into India, Thailand, the Philippines, the US, and – earlier this week – South Korea, we now have a clearer snapshot of Jack Ma’s playbook.
1. Go after people not served by banks. There are a lot of them.
When Ant Financial last month picked up US-based Moneygram for US$880 million, it wasn’t going after American consumers – it had its eye on the migrant workers who need to wire home money to the 200 countries where it has outlets.
The US is the biggest source country for remittances. Globally, migrant workers sent home US$432 billion in 2015 – well up on US$332 billion five years prior, according to the World Bank.
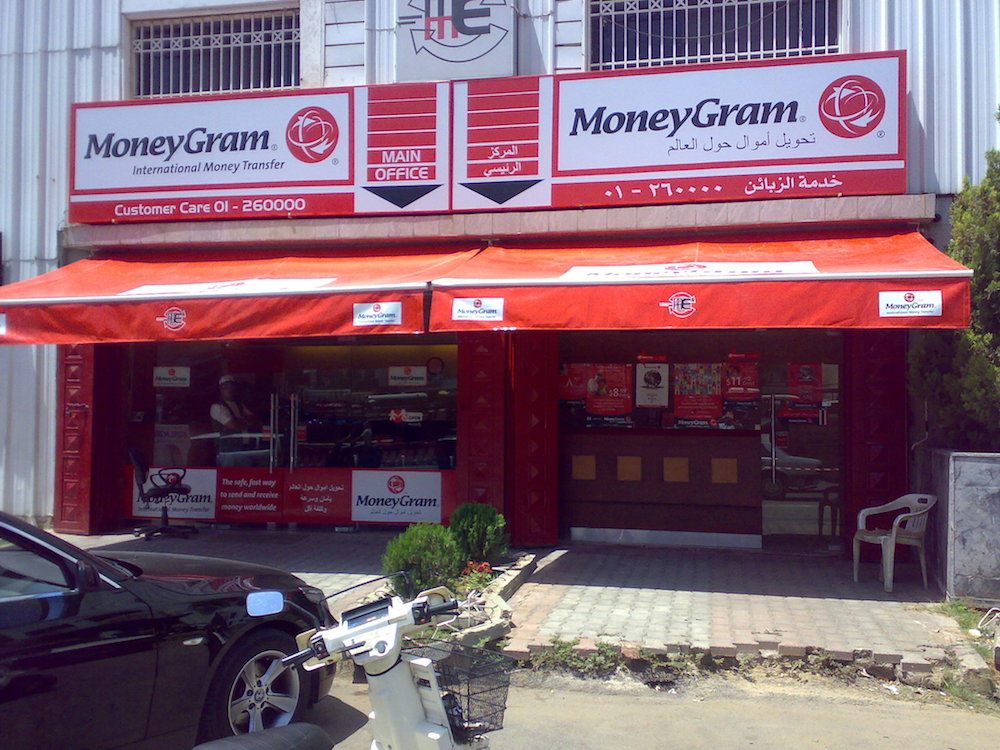
A Moneygram outlet in Beirut. Photo credit: Panoramio.
Only 12 percent of Moneygram’s revenue from transfers derives from US consumers sending cash within the country – 38 percent of it is outbound transfers, while the remaining half is all outside the US. As with all major money wiring services, the recipients don’t need to have a bank account.
In this way, Ant Financial is after the so-called unbanked population – people with little or nothing in the way of financial services, often not even debit or credit cards, from the traditional banking sector.
Ant’s four investments for expansion across Asia further prove that.
Funded AF





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.