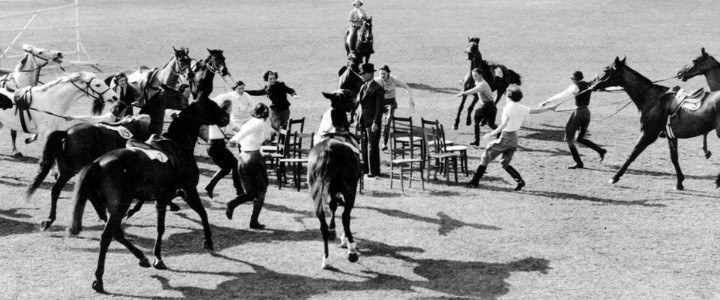
Image credit: State Library of South Australia
Are we experiencing another tech bubble, or the biggest secular move of the digital economy since the integrated circuit? This debate rages across Silicon Valley, India and the global industry, with both sides creating many convincing presentations, articles and tweetstorms to support their view and refute the other.
The truth is a bit more complicated. First, we cannot refute today’s secular changes. Internet penetrates every aspect of daily life and business. In 2014, over 2.4 billion people were using the Internet and more than 8.7 billion devices were connected, a huge leap from the Internet’s 50 million users in 1998. The way users access the Internet has also changed, thanks to the rise of mobile.
Still, layered across these major shifts are significant indicators of a potential bubble. We see 5, 10, or even 20 me-too startups chasing the winner-takes-most markets where the winner is already established. At the same time these startups burn more quickly due to monstrous amounts of late-stage capital.
Increasingly, we see new investors entering at stages with which they have no experience and entrepreneurs feeling the pressure to grow before they have basic proof of product market fit, let alone unit economics.
If you take a step back to analyze the mindset, you’ll find analogous behavior across the long history of startups. Outrageously optimistic predictions have long taken the place of reasonable consideration of risk. Going back to the first integrated circuit, countless waves of opportunity have sprung to such heights that, at some point, everyone thinks they can win.
This continues until the market of risk-taking hits its limit, providing an expensive “education.” History has shown that the natural scale of economies and branding allow only one or two companies in a sector to win big. The rest will fight over table scraps. Some will be acquired or consolidated. Most will fail.
We understand that today’s startups are engaged in a game of musical chairs, and we design our strategy to retain a chair for our entrepreneurs to dominate new markets. The unique formula for a winning company rests on four pillars: unit profitability, restrained burn rates, capital stability, and contingency planning. Companies with these four pillars under their seat are more likely to wind up in a chair when the bubble stops.
1. Unit Profitability
Mentions of the lean startup seem rare these days, even though this model has proven a winning formula time and time again. Being able to achieve product market fit and positive return on sales, without massive amounts of capital, is highly predictive of success and the best inoculation against capital “bubbles”.
2. Restrained Burn Rates
While it costs less than ever before to start a company, and seed capital flows freely, this is not a free pass on following burn rates. There are many well-documented examples across industries and cycles where the winning companies started, and often finished, with far less capital raised than their “also-ran” competitors.
We’ve seen a similar trajectory for some our companies too. This isn’t to say that companies should be undercapitalized, but scarcity and respect for capital do drive innovative thinking and focus. Both are keys to success at any point in the cycle.
3. Capital Stability
Once unit economics are positive and repeatable, burn rates become more of a choice relative to growth, not a survival necessity. With solid unit economics and proof of product market fit, the core engine of a company is typically ready to accelerate towards leading market share.
This is when capital stability pays off, starting with a solid Seed/Series A syndicate. We believe the best foundation is a syndicate of two institutional investors possessing the dry powder and conviction to support initial growth and the credibility to attract high-quality growth investors when it’s time to pour on the gas.
4. Contingency Planning
Even in buoyant times, a precautionary assessment of the unexpected remains valuable. For example, if you’re expanding nationally while still trying to prove product market fit or still seeking solid unit economics. In this instance, your burn is likely very high, making your reliance on attracting additional capital more absolute, and potentially more difficult.





Stay updated on the go with our mobile app.
Get latest insights with smoother, more personalized experience through TIA mobile app.







📅 Upcoming Events
22 October 2026
Payoneer x CSPN Summit 2026