Summary:
- AI changes the cost equation. Unlike traditional SaaS, every prompt, API call, or agentic task can carry a marginal cost, making usage part of the business model.
- Free-trial abuse can hit margins before revenue comes in. Multiple accounts, token theft, and pay-as-you-go abuse can consume real compute, pushing risk prevention further upstream.
- Commercial infrastructure needs to keep pace with agents. As agents take on more of the building and operating process, payments, permissions, metering, and risk controls may need to come in earlier.
- Learn more about how Stripe Radar helps businesses detect AI-related abuse and protect revenue.
A free trial used to be a fairly cheap bet.
Want to know how a product works? Try it. Don’t like it? Stop subscribing. For traditional SaaS companies, what’s the worst outcome? A user just doesn’t convert.
“Software used to be expensive to build, but cheap to serve,” says Sarita Singh, regional head and managing director for Southeast Asia, Greater China and South Korea at programmatic financial infrastructure platform Stripe. Once the software was built, serving one more user generally added little cost.
AI flips that equation: Every prompt, API call, or task carried out by an agent can consume compute. So a user who never pays can leave behind more than lost revenue.
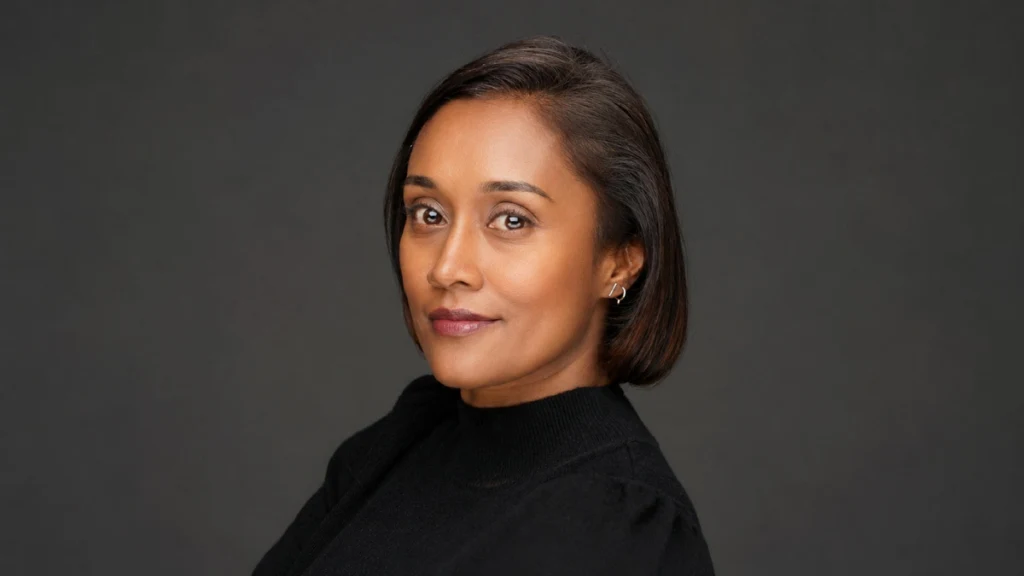
Sarita Singh, regional head and managing director for Southeast Asia, Greater China and South Korea at Stripe / Photo credit: Stripe
“Software is now much cheaper to build, but every interaction can carry a real cost,” she adds.
The cost of free
Across Stripe’s network, more than one in six sign-ups at AI companies are linked to multiple account abuse. Free-trial abuse more than doubled in six months, while its Radar fraud prevention system blocked 3.3 million risky free trials across eight AI companies in one month.
Fraud, in that sense, is no longer limited to stolen payment details. Users can create multiple accounts to repeatedly claim free credits, exploit pay-as-you-go models, or consume AI tokens without paying.
These actions “can consume real compute before a business collects revenue,” Singh says.
Timing matters here. Traditional payment fraud might only surface at checkout, when a credit card is declined. But for an AI company, waiting until that point can mean it has already paid for that usage.
As such, risk prevention needs to move further upstream while costly resources are still being consumed, Singh notes. Left unchecked, the abuse could eat into a company’s margins too.
Rethinking the price tag
The same variable-cost economics also makes legitimate customers harder to price, as no two users consume an AI product the same way.
An engineer leaving several agents running overnight and someone occasionally using the same tool for research might both be paying customers, but the costs they generate and the value they get can differ considerably.
“With AI, the value a customer gets is highly variable,” Singh says. “Flat pricing struggles to account for that.”
Photo credit: m.dipo / Shutterstock
Companies are responding with a wider mix of subscriptions, usage-based models, token pricing, and outcome-based pricing, where customers pay proportionately to work completed. Two in three companies on the Forbes AI 50 are already leveraging some form of usage-based pricing, according to Stripe’s data.
For hybrid pricing to work, however, businesses need to understand what users consume, what it costs to serve them, and how the economics differ across customer groups. That requires reliable metering, usage caps, forecasting, and visibility into margins.
However, that doesn’t mean companies should abandon subscriptions overnight, as Singh sees the shift happening more gradually.
“Instrument first, learn the distribution of value and cost, test with cohorts, then evolve the model,” she says.
All about the base
At the recent Tech in Asia Conference in Singapore, Singh spoke with backend infrastructure company Supabase co-founder Paul Copplestone, who estimates that around 90% of projects launched on its platform involve some form of agentic workflow.
That has fundamentally changed how Supabase designs its products, shifting toward code-first workflows that agents can interact with more directly.
“We made the decision to go from kind of dashboard first to code first,” Copplestone says. “Everything needs to live in code.”
Agents are taking on more of software setup and provisioning that developers once handled manually. While that shortens the path from build to launch, payments and monetization need to become part of the development process sooner.
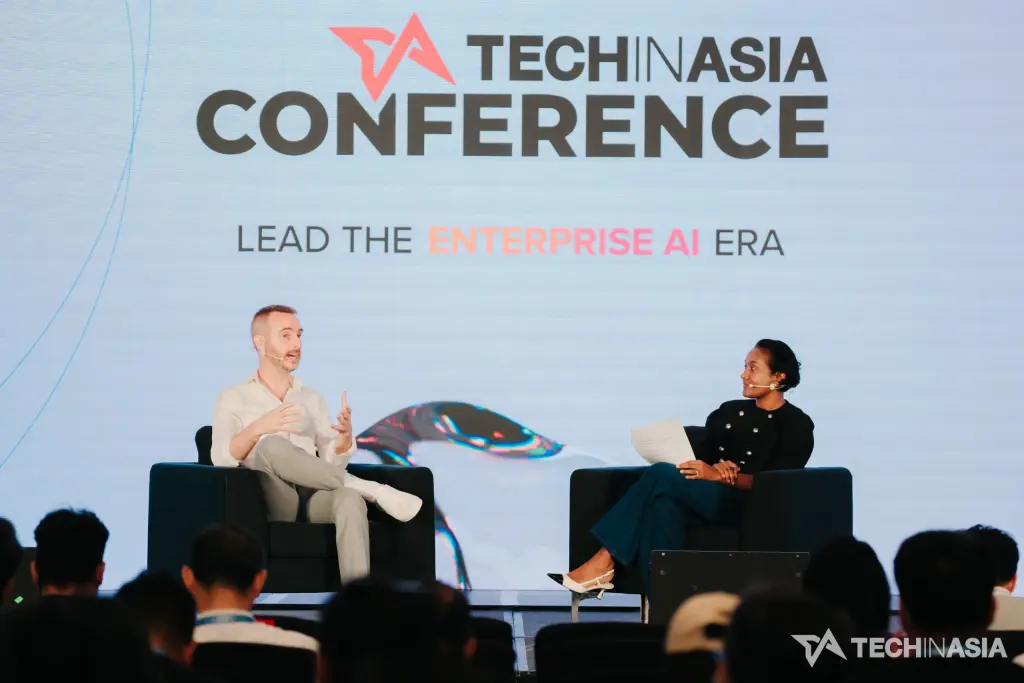
Singh and Copplestone in discussion at Tech in Asia Conference / Photo credit: Tech in Asia
The Stripe and Supabase collaboration on Stripe Projects is one such example. It allows developers and coding agents to provision Supabase services alongside payment infrastructure through the same workflow, reducing the handoff between building a product and preparing it to generate revenue.
To this end, Copplestone views the two companies as playing complementary roles: Supabase helps users through the “builder mentality” while Stripe helps through the “entrepreneur mentality.”
Trust at machine speed
As building becomes more automated, AI agents can operate with fewer human checkpoints or pauses for manual approval.
Establishing trust becomes essential, and a credential alone does not suffice. “Authority has to be explicitly granted, scoped, enforced, and auditable,” Singh stresses.
That could include spending or category limits, approval for higher-risk actions, scoped credentials, and a clear audit trail of agent activity.
But more than a single fraud tool or pricing framework, businesses increasingly need infrastructure that can scale and respond at the same pace as the agents.
“Merchants need risk defenses built for machine speed,” says Singh.
Stripe provides the financial infrastructure to help businesses build, price, protect, and scale in the internet economy. As AI agents increasingly act and transact on behalf of users and businesses, Stripe helps companies manage the payments, revenue, and fraud challenges of machine-speed commerce.
Find out how Stripe Radar can help your business.
This content was produced by Tech in Asia Studios, which connects brands with Asia’s tech community. Learn more about partnering with Tech in Asia Studios.
Editing by Stefanie Yeo and Eileen C. Ang
(And yes, we’re serious about ethics and transparency. More information here.)

📅 Upcoming Events
30-31 March 2027
Upskill Fest